Empowering rural entrepreneurs: how digital startups are solving the microfinance crisis
Across the world, millions of small business owners in rural and underserved communities struggle to access the financial tools they need to grow. Traditional banking systems have long fallen short of serving those who live far from urban centres, leaving entrepreneurs without credit, capital, or guidance. Yet a quiet revolution is under way, driven by digital startups and fintech innovation that are reshaping the landscape of microfinance and financial inclusion.
In short
- Digital startups and fintech innovations are addressing the systemic exclusion of rural entrepreneurs from traditional banking by providing critical access to capital.
- The rapid expansion of digital financial services, particularly in markets like India, has enabled millions to transition from cash-based economies to digital transactions.
- Technology alone is insufficient for financial inclusion; sustainable growth requires user-centric design that accounts for low financial literacy and local community needs.
- Leading fintech initiatives now combine credit access with comprehensive support, including mentorship, education, and networking, to foster long-term business success.
- Digital platforms are breaking down geographic barriers by connecting remote entrepreneurs with global investor networks, facilitating a more democratic distribution of capital.
- Successful rural financial solutions prioritize localized user experiences, such as intuitive interfaces and multi-language support, to ensure tools remain relevant and accessible.
- The integration of digital innovation with sustainable social entrepreneurship is redefining economic development, moving beyond mere survival toward long-term resilience and ecological progress.
Bridging the Financial Gap in Abandoned Regions
In many parts of the world, rural populations have historically been excluded from formal financial systems. Whether due to poor infrastructure, low financial literacy, or a simple mismatch between available services and genuine community needs, the gap between those with access to credit and those without has remained stubbornly wide. The situation is particularly acute for women entrepreneurs, who face compounding barriers when seeking microcredit or small business funding. Research examining the experiences of hundreds of women entrepreneurs across several countries has highlighted the acute difficulties they faced with microfinance loans, challenges that were present long before recent global crises and only intensified thereafter.
Leveraging fintech innovation for local business growth
The rise of digital financial services has begun to address some of these entrenched problems. In markets such as India, digital disbursal has fundamentally transformed how microfinance institutions reach the rural population. The numbers paint a striking picture: since 2011, over a billion adults worldwide have opened bank accounts, with more than half a billion doing so in just the last few years of that period. By a recent measure, nearly seven in ten people now use digital channels for financial transactions, a shift that would have been unthinkable just a decade ago. In one reported quarter, the overwhelming majority of loans in India were disbursed digitally, representing thousands of crores of rupees across millions of loan accounts, a testament to what mobile banking and cashless transactions can achieve at scale.
Overcoming traditional banking challenges in rural areas
Despite this progress, significant obstacles remain. Poor accessibility, limited awareness of available products, and low financial literacy continue to hold back millions. In India alone, over 240 million people have mobile phone access, yet many do not actively use bank accounts, largely because the services on offer do not reflect their actual lives or needs. Government schemes designed to bring rural citizens into the financial mainstream have had limited impact in practice, underlining the fact that technology alone is insufficient without thoughtful design and genuine community engagement. Inclusive finance demands more than connectivity, it requires trust, relevance, and sustained support.
Building sustainable digital ecosystems for local founders
Beyond simply providing loans, the most forward-thinking actors in the digital economy are building entire ecosystems around rural and emerging entrepreneurs. This means combining access to credit with mentoring, networking, and practical education, creating environments in which small businesses can genuinely flourish rather than simply survive. The goal is sustainable livelihoods and long-term economic independence, not merely short-term relief.
Tailored Mentoring and Practical Workshops for Success
A growing number of incubators and startup support programmes now offer personalised workshops and practical mentoring to entrepreneurs navigating the complexities of launching and scaling a business in underserved areas. These programmes recognise that the challenges faced by a rural founder are fundamentally different from those of an urban counterpart, and that cookie-cutter solutions rarely stick. By tailoring their offer to the specific context of each participant (their sector, their community, their access to technology) these initiatives are producing a new generation of resilient, digitally literate business owners. The benefits extend well beyond the individual, rippling outwards to strengthen entire local economies.
Connecting regional innovators with global investor networks
One of the most transformative shifts in recent years has been the growing willingness of investors to look beyond traditional urban hubs when seeking promising opportunities. Digital platforms and networking tools now make it possible for an entrepreneur in a remote region to pitch to an investor on the other side of the world, breaking down the geographic barriers that once made rural entrepreneurship a lonely and underfunded endeavour. This democratisation of capital is not without its challenges (questions of due diligence, cultural context, and genuine impact remain live debates) but the direction of travel is clear. Gender empowerment is increasingly central to this conversation, with dedicated programmes focused on ensuring that women entrepreneurs are not left behind as these new networks take shape.
Driving economic transition through technological support
The intersection of technology and rural economic development is producing outcomes that go beyond simple financial metrics. Digital tools are enabling communities to participate in broader economic transitions, from the shift towards more sustainable production methods to the adoption of artificial intelligence and data-driven decision-making at the micro level. For entrepreneurs in isolated areas, these innovations are not abstract future possibilities, they are practical solutions to immediate problems.
Enhancing the User Experience for Community Enterprise
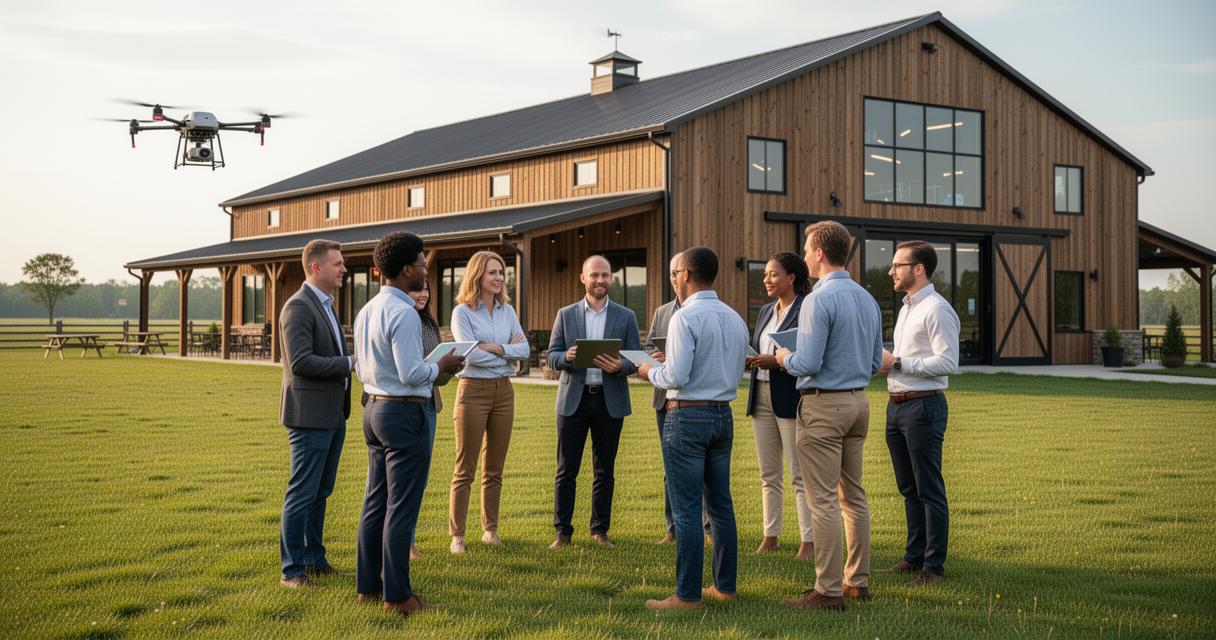
A recurring theme in the most successful digital lending and fintech initiatives is the primacy of user experience. Products designed with the end user in mind (intuitive, accessible, available in local languages, and sensitive to low-bandwidth environments) consistently outperform those developed without that consideration. The lesson for the broader fintech sector is clear: financial inclusion is not achieved by transplanting urban solutions into rural contexts, but by genuinely understanding and responding to the specific needs of each community. When the technology works for the people it is meant to serve, the results in terms of small business funding, economic participation, and community resilience speak for themselves.
Fostering Resilience and Ecological Progress in Regional Hubs
Looking ahead, the most promising developments lie at the convergence of digital innovation, ecological transition, and social entrepreneurship. Regional hubs are emerging as laboratories for a new kind of growth, one that values sustainability alongside profitability, and community impact alongside individual gain. Digital startups operating in this space are not simply solving the microfinance crisis; they are helping to redefine what economic success looks like for the millions of entrepreneurs who have long been overlooked by the mainstream. As mobile banking, data connectivity, and tailored support continue to improve, the prospect of genuinely inclusive rural economic development (once a distant aspiration) grows ever more tangible.
 Top 10 COSHH Signage Suppliers in the UK Compared: Is Seton.co.uk Still the Best Choice in 2026?
 Why mon kit solaire makes community solar projects accessible for every british household
 Top 7 best safety signs in 2026: A comparison of Seton, Jalite, Stocksigns, Viking Signs, SafetySigns4Less, Messagemaker, and The Sign Shed
 Top 4 Best ISO 7010 Signage Providers in the UK for Workplace Compliance in 2026